
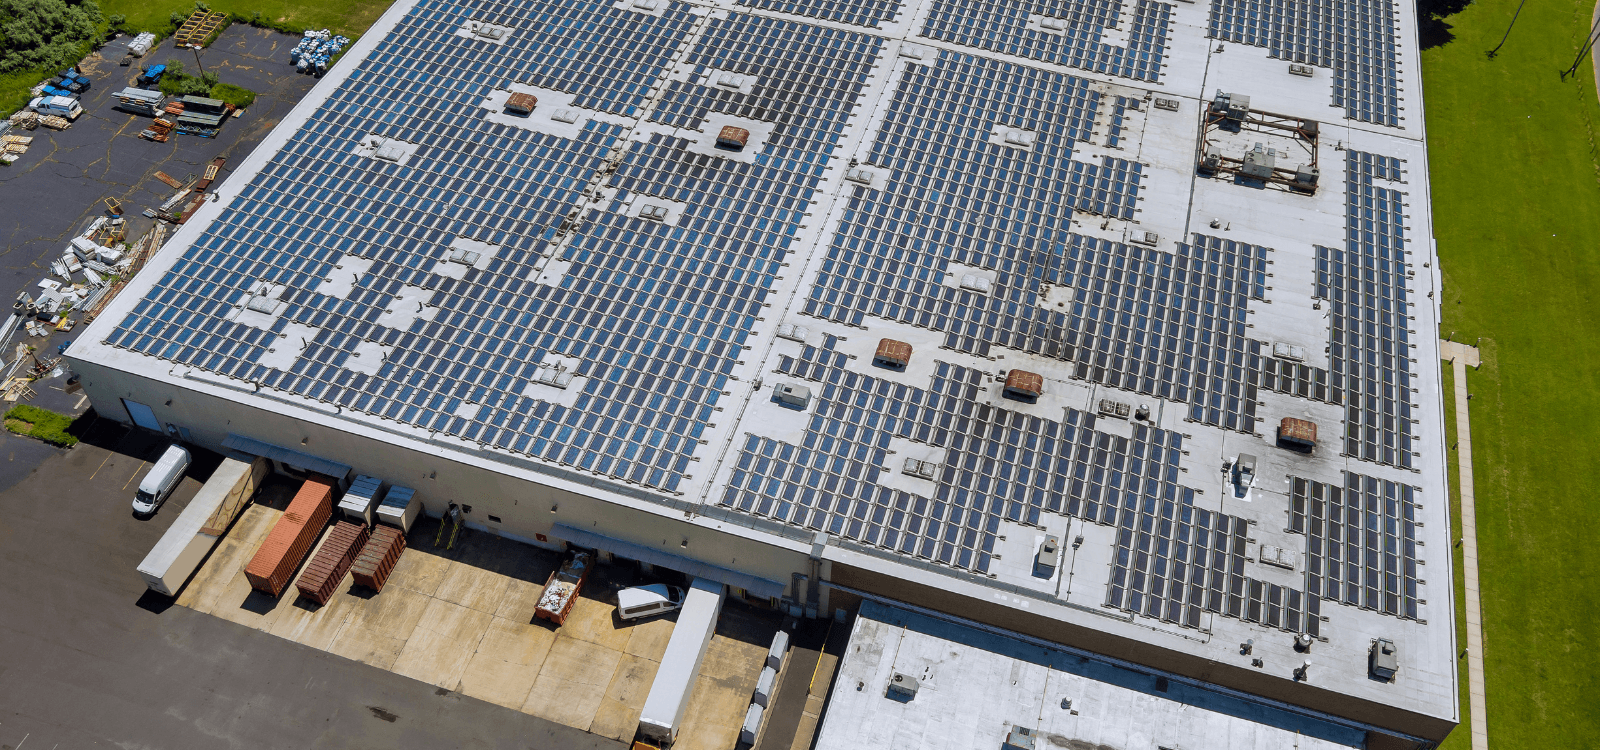
Solar rarely lands on an M&A due diligence checklist. What to check when a commercial solar system surfaces mid-deal, and who owns the decom bill.
You're buying a company, or the real estate under it. Somewhere in that deal there's an existing solar system nobody put on the checklist.
It happens more often than deal teams expect. Solar rarely appears on a standard real estate or M&A due diligence checklist, and it's easy to wave off as "some panels somewhere on the property" instead of an actual asset with its own contracts, liens, and liabilities.
Then diligence turns up a solar agreement, an interconnection agreement with the utility, a site lease that needs consent before it can be assigned, or a UCC-1 filing against the equipment that has to be released before the deal can close cleanly. Sometimes the problem is simpler than that. Nobody can produce a clear chain of title showing who actually owns the system.
Now it's a surprise line item in a deal you thought was fully scoped.
Why Doesn't Solar Show Up on a Standard Diligence Checklist?
Existing solar gets missed because it doesn't sit cleanly inside any one diligence workstream — it isn't quite real property, it isn't ordinary equipment, and it's often owned or financed by a third party who isn't a seller in your transaction.
Real estate counsel reviews title, survey, leases, and environmental. Corporate counsel reviews the cap table, material contracts, and debt. A rooftop array financed through a third-party ownership structure a decade ago can fall between those two reviews and never get pulled into either one.
The systems most likely to surprise a deal team are the ones built in the 2010s under state incentive programs. The original installer may be out of business, the lender may have sold the note, and the property may have traded once or twice since the system went live. That's usually why nobody on either side of the table can answer basic questions about it.
What Documents Actually Control an Existing Solar System?
Once solar surfaces, the first job is finding the paper. A commercial system typically carries several agreements, and they rarely live in the same file — which is why tracking down the original contract terms is often the longest part of the exercise.
- ●Power purchase agreement or equipment lease. If the system is third-party owned, this is the contract that governs who gets the power, at what price, and for how long. It also usually contains the assignment and change-of-control language that matters most to your closing.
- ●Interconnection agreement. The contract with the utility that permits the system to connect and export to the grid. It's tied to the meter and the site, and transferring it usually means notifying or re-papering with the utility.
- ●Site lease or roof license. The document giving the system owner the right to occupy the roof, the parking canopy, or the ground. Consent to assign is common here, and a missing consent stalls a closing.
- ●UCC-1 financing statement. A lien filed against the equipment by whoever financed it. It has to be released or expressly assumed, and a stale filing against a paid-off system still shows up in a search.
- ●O&M and monitoring agreements. Service contracts that may have lapsed years ago. Their absence tells you the system likely hasn't been maintained or watched.
- ●Incentive registrations. SREC accounts, net metering enrollment, or state program registrations that carry real revenue and are usually registered to a party name, not a parcel.
The asset itself is straightforward. The paperwork around it usually isn't.
Who Actually Owns the Solar System?
In a meaningful share of these deals, the honest answer at the start of diligence is that nobody knows — and unclear ownership, not the hardware, is what turns a solar system into a deal issue.
Third-party ownership was the dominant model for commercial solar in the 2010s. The developer built it, a tax equity investor held it, a lender financed it, and a servicer administered it. Any of those parties may have merged, sold their position, or wound down since.
The result is a system on a property where nobody is clearly responsible for it anymore. The seller assumes it conveys with the building. The buyer assumes the seller has documentation. Neither assumption survives a title search.
What Happens If the Contracts Don't Assign Cleanly?
Assignment is where a small item becomes a schedule item. Most solar agreements were drafted to protect the system owner's economics, so they include consent rights, notice periods, and change-of-control provisions that trigger on exactly the transaction you're trying to close.
Chasing a consent from a counterparty who no longer has an active team on the account takes weeks, not days. That is the mechanism by which a rooftop system stalls a real estate closing — not the panels, the signature.
The practical consequences show up in three places. Legal has to determine whether each agreement transfers. Finance has to decide whether the system is an asset, a liability, or a rounding error. And the deal team has to decide whether to reprice, escrow, carve the system out, or hold the closing.
Who Pays to Decommission the System at End of Life?
Unless the purchase agreement assigns it to someone specific, decommissioning falls to whoever owns the property on the day the system finally quits. Removal, disposal, and recycling are real costs, and they don't disappear because the contract was silent.
This is the question nobody at the table wants to be the one holding. It gets passed down deal after deal, quietly, until an owner who had nothing to do with the original installation gets the bill.
States are starting to formalize the obligation rather than leave it to private agreements. Pennsylvania's Act 44, for example, requires decommissioning plans and financial assurance for solar projects over 2 MW. Where a rule like that applies, the liability becomes explicit, which is better for diligence but harder to ignore.
What Are a Deal Team's Options?
Four paths show up repeatedly, and they carry different amounts of residual risk.
- ●Take it as-is. Fastest, and appropriate when documentation is clean and the system is producing. It leaves the end-of-life obligation with the buyer.
- ●Reprice or escrow. Hold back against unknown assignment costs, deferred maintenance, or removal. This works only if someone can put a defensible number on those items.
- ●Carve the system out. Exclude it from the transaction and leave it with the seller. Clean on paper, but it requires a party willing to keep owning an orphaned asset on someone else's property.
- ●Sell the system to a specialist buyer. Move the asset, the contracts, and the decommissioning obligation to a party that does this for a living, either alongside your closing or immediately after it.
Start With a Real Number Before You Reprice the Deal
The reason a straightforward asset feels like a landmine is that nobody on the deal team does this for a living. We do. We buy existing commercial solar systems that surface during diligence — rooftop, parking canopy, or ground-mounted — and we work through unclear titles, UCC-1s that need releasing, contracts that don't assign cleanly, and decommissioning costs nobody wants to inherit.
We can move fast enough to close alongside your transaction, take the system off the cap table entirely, or step in post-close and take the liability, including the eventual decommissioning bill, permanently off your hands.
If solar surfaced in your diligence and nobody on your team wants to own it, send us the basics and we'll come back with a real number: zip code, project type, system size, and the year it went live. You can also see what the system may be worth in a couple of minutes.
Ready to Discuss Your Project?
Get your instant estimate or talk to our team about your legacy solar project.


